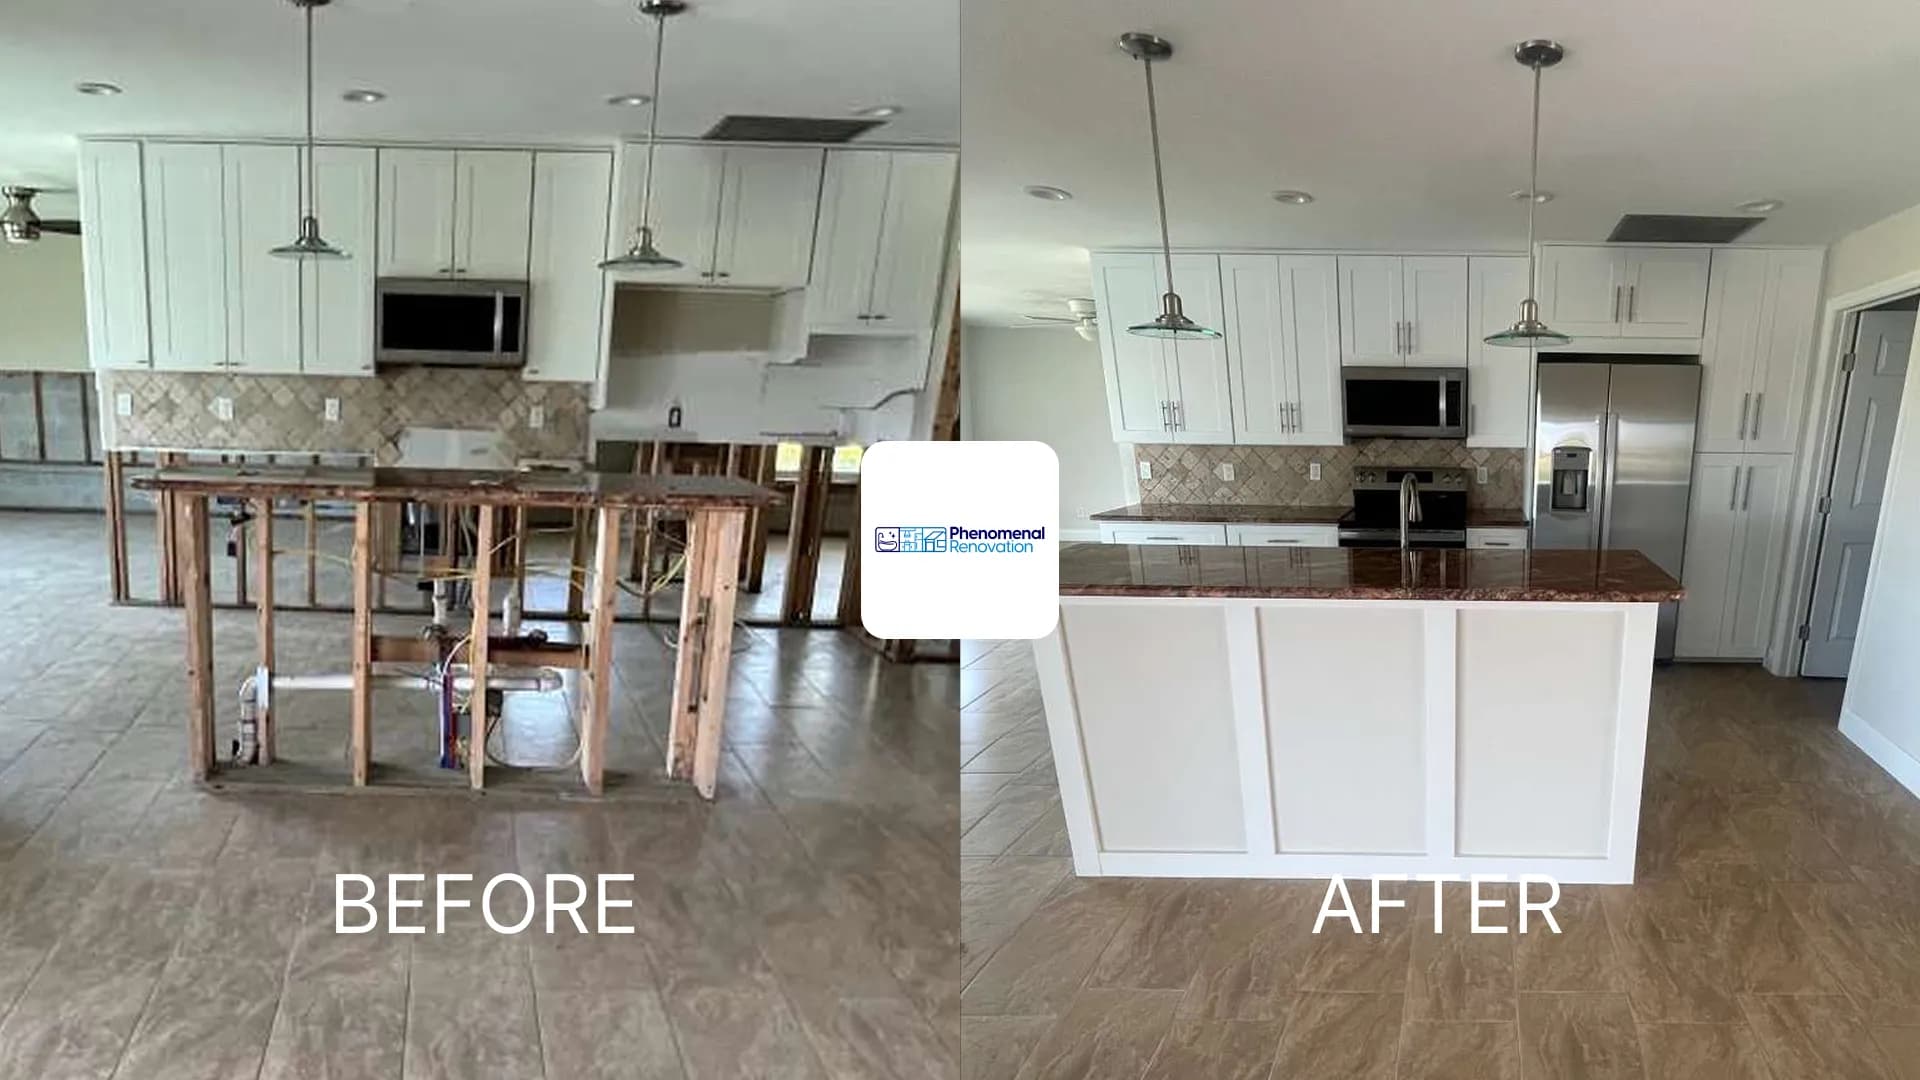
Is Financing a Home Remodel Worth It? A Bonita Springs Homeowner's Guide
Is financing a home remodel worth it? Compare HELOCs, home equity loans, personal loans and cash-out refinancing before you borrow in Bonita Springs.
Overview
You have a kitchen that no longer works, a bathroom that leaks, or a house that needs a full refresh, and the estimate is bigger than your savings account. Is financing a home remodel worth it, or is waiting the smarter move? For many Bonita Springs homeowners, financing a home remodel is a sensible tool when the project protects the home, improves daily life, and fits comfortably inside the monthly budget. For others, borrowing turns a good idea into a long-term burden. This guide compares the main ways of financing a home remodel, uses real payment math, and gives you a simple test for deciding. It is general information, not financial or tax advice, so confirm details with a lender and a tax professional. Whether you are financing a remodel for one room or the whole house, the same questions apply.
Quick answer: Financing a home remodel is usually worth it when the project is a need or a value-adding upgrade, the monthly payment fits your budget with room to spare, and the interest rate is reasonable. Home remodel financing is usually not worth it for purely cosmetic luxuries or when the loan would stretch your finances thin.
Home Equity Loan vs HELOC: How Each Works for a Remodel
Home equity loan vs HELOC is the first comparison most homeowners make when financing a home remodel, because both borrow against the equity you have built. A home equity loan gives you a lump sum at a fixed rate with fixed monthly payments. A home equity line of credit, or HELOC, works like a credit line: you draw what you need, when you need it, and the rate is usually variable.
When comparing a home equity loan vs HELOC, think about how your project unfolds:
- Home equity loan. Best when you have a fixed-price bid and want predictable payments. You pay interest on the full amount from day one.
- HELOC. Best for phased work or uncertain costs, since you pay interest only on what you draw. The variable rate can rise, and the draw period often starts with interest-only payments.
- Shared risks. In the home equity loan vs HELOC choice, both are secured by your home, and closing costs can add up to a few thousand dollars.
Because home remodel financing through equity usually carries the lowest rates, it is the first place most homeowners look. National averages reported this fall sit roughly between 7.5% and 8.5% for both products, depending on the source and the loan term, according to Experian's rate summary. Many lenders cap total borrowing at about 80-85% of your home's value, so your equity decides how much you can access. Weighing a home equity loan vs HELOC against your timeline is a core step in financing a home remodel.
Personal Loan for Home Improvement: Fast, Unsecured, Pricier
A personal loan for home improvement does not use your house as collateral, and funding can happen in days instead of weeks. That makes a personal loan for home improvement attractive for smaller projects, such as a bathroom refresh or new flooring, and for homeowners without much equity. That speed makes this kind of home remodel financing popular, but the trade-off is cost: rates are often in the double digits and terms are shorter, so monthly payments run higher.
Here is how the math plays out. A $25,000 personal loan at 12% over five years costs roughly $556 a month and about $8,400 in interest. Those numbers can be fine for a modest project, and a fast, unsecured route to financing a remodel can be the right call, yet the same approach on a $60,000 renovation would strain most budgets. Check for origination fees, prepayment penalties, and maximum loan amounts, since many lenders cap a personal loan for home improvement at 50,000.
Contractor or retailer payment plans deserve extra scrutiny. Ask for the APR, the term, and whether interest is deferred and charged retroactively if you miss the promotional deadline. Whichever route you take when financing a home remodel, bring a detailed written estimate so the lender and you both see the full scope.
Cash-Out Refinance and Renovation Loans: When They Make Sense
A cash-out refinance replaces your current mortgage with a larger one and hands you the difference in cash, making it the biggest-scale way of financing a home remodel. It can make sense when your existing rate is higher than today's rates or when you need a large sum for a whole home renovation. If your current mortgage rate is lower than what lenders offer now, a cash-out refinance can raise the cost of your entire mortgage, not just the renovation. Closing costs, often a few percent of the new loan, also apply. Treat any cash-out refinance as financing a remodel with your entire mortgage, not just a project loan.
Renovation-specific mortgages are another path to financing a home remodel. The FHA 203(k) program and Fannie Mae's HomeStyle loan roll renovation costs into a purchase or refinance. They suit buyers of older Bonita Springs homes that need work, but they come with more paperwork, plan requirements, and contractor approvals. A cash-out refinance or renovation loan is worth comparing against a home equity loan, because the better option depends on your existing mortgage rate and the size of the project. If your project is large, our whole home renovation guide explains timelines and contingency planning that lenders will ask about.
When Financing a Home Remodel Is Worth It (and When It Is Not)
Financing a home remodel is worth it when borrowing solves a real problem or adds lasting value. Use this test before you sign, because financing your remodel is worth it only when most of these are true:
- The project is a need or a smart upgrade. Water damage, failing plumbing, safety issues, or a dated kitchen that hurts resale justify borrowing more than a luxury add-on.
- The payment fits with room to spare. Run the numbers: $50,000 at 8% over 15 years is about $478 a month and roughly $36,000 in interest, while a 10-year term is about $607 a month and roughly $22,800 in interest. A shorter term costs less overall if you can handle the payment.
- You still have an emergency fund. Florida homeowners face insurance deductibles and storm-season surprises, so do not drain your reserves, even when financing a home remodel.
- The return makes sense. Compare the cost with what the project may recover, because financing a remodel is worth it more often when the upgrade recoups much of its cost. Our guide to home improvement ROI in Cape Coral shows that focused updates typically recoup more than big luxury builds.
Ask yourself directly: is financing a home remodel worth it for this project, at this rate, today? It is not when the loan only funds trends, stretches your budget, or could be avoided by phasing the work. Saving for part of the project, or tackling one room at a time, often costs less and shrinks the amount you need when financing a remodel. In short, financing a home remodel is worth it when the numbers and the need agree. Interest on home equity debt may be deductible only when the funds are used to substantially improve the home, so review IRS Publication 936 or ask a tax professional. For project pricing, see our kitchen remodel cost guide and our look at bathroom remodel cost in Fort Myers.
Frequently Asked Questions
Is it smart to finance a kitchen or bathroom remodel?
It can be, if the project improves function or value and the payment fits your budget. Kitchens and bathrooms are among the most common reasons for financing a home remodel, so compare at least two lenders before choosing.
Is a HELOC or a personal loan better for a remodel?
A HELOC usually offers a lower rate and larger limits but uses your home as collateral. A personal loan funds faster and keeps your house out of the deal, but costs more per month. When financing a home remodel, larger projects tend to favor home equity borrowing, and smaller ones favor personal loans.
How much equity do I need to borrow for a remodel?
Many lenders require you to keep roughly 15-20% equity after the new loan, which means total borrowing is capped near 80-85% of your home's value when financing a home remodel. Requirements vary by lender and credit profile.
Can I deduct interest when financing a home remodel?
Possibly. Interest on home equity debt may be deductible if you itemize and use the money to buy, build, or substantially improve the home that secures the loan. Confirm with a tax professional.
Conclusion: Decide Before You Borrow
So, is financing a home remodel worth it? It is when the work protects or improves your home, the numbers fit your budget, and you have compared your options, including a home equity loan, HELOC, personal loan, and cash-out refinance. Financing a home remodel is a tool, not a goal, and the right amount is the smallest one that gets the job done well. Smart remodel financing always starts with a clear scope and a written estimate.
Phenomenal Renovation is led by Cristiano Barbosa, a Florida Certified Residential Contractor and licensed plumber, and every project is backed by a written warranty. Call (239) 878-3404 or request a free estimate to get a clear scope and price before you talk to a lender. Learn more about our work in Bonita Springs, or read our guide to kitchen remodeling in Bonita Springs.
Cristiano Barbosa is the Founder & CEO of Phenomenal Renovation, a family-owned remodeling company serving Fort Myers, Cape Coral, Naples, Bonita Springs, Estero, and LaBelle. With over 20 years of hands-on experience and two generations of construction knowledge behind him, he holds both a Certified Residential Contractor (CRC) license and a Licensed Plumber license, letting his crew handle plumbing and waterproofing in-house instead of outsourcing it, and has led his team through more than 350 successful renovations across Southwest Florida.